
Blue Peak Risk Advisors
Your homeowners and auto insurance policies provide important protection, but their liability limits may not always reflect the level of financial exposure you could face. Umbrella insurance can provide an additional layer of personal liability protection above certain underlying policies, helping eligible individuals and families address larger covered claims according to the policy terms.
An umbrella policy is designed to work alongside underlying insurance rather than replace it. Depending on the policy, it may provide additional liability protection when the limits of certain qualifying home, auto, or other underlying policies have been exhausted.
Blue Peak Risk Advisors helps individuals and families review their liability exposure and compare available umbrella insurance options. Whether you own a home, operate multiple vehicles, have significant assets, own rental property, or simply want to evaluate your existing liability protection, understanding how an umbrella policy works can help you make a more informed decision.
An umbrella policy can provide an additional layer of liability protection above certain underlying policy limits.
Review your existing home, auto, and other qualifying policies to understand how additional liability protection may fit into your overall insurance structure.
Compare available umbrella insurance options from multiple carriers based on eligibility, coverage requirements, limits, and pricing.
Your liability exposure can change as your assets, properties, vehicles, and other circumstances change.
OUR INSURANCE SOLUTIONS
Umbrella insurance is designed to provide additional personal liability protection beyond the limits of certain underlying insurance policies. It is generally considered supplemental coverage rather than a replacement for homeowners, auto, or other primary insurance.
The primary purpose of an umbrella policy is to provide additional liability limits when a covered claim exceeds the liability limit available through an underlying policy. For example, a serious accident involving your vehicle could potentially result in substantial bodily injury or property damage claims. Your underlying auto policy would respond according.
Depending on the policy, umbrella coverage may apply to certain personal liability exposures beyond those associated with your home or vehicle. Coverage can vary significantly between policies, so it is important to review the specific terms, exclusions, conditions, and underlying insurance requirements before selecting an option.
Individuals with several properties, multiple vehicles, rental properties, significant personal assets, or other potential liability exposures may have more reasons to evaluate additional liability protection. An umbrella policy can potentially coordinate with qualifying underlying policies to provide an additional layer of protection across eligible exposures.
Umbrella policies generally require certain underlying insurance coverage to be maintained at specified limits. This can include qualifying homeowners or auto liability coverage depending on the policy. Maintaining the required underlying coverage is therefore an important part of keeping an umbrella policy properly structured.
An umbrella policy does not automatically cover every type of loss or liability. Policies have limits, exclusions, conditions, and other provisions that determine when coverage applies. Understanding these details is essential when comparing umbrella policy coverage and evaluating what protection a particular policy may provide.
Coverage For Businesses Of All Sizes
The umbrella insurance cost can vary depending on the individual’s circumstances and the amount and type of coverage selected.
Insurers may consider factors such as the number of properties, vehicles, household drivers, underlying insurance limits, claims history, personal circumstances, and the selected umbrella limit when evaluating available options.
The cost should also be considered alongside the protection being provided. A policy with a lower premium may have different limits, exclusions, requirements, or coverage provisions from another policy.
This is why comparing umbrella policies based solely on price may not provide a complete picture. Understanding the underlying insurance requirements and the scope of the protection can be equally important.
Your existing liability limits can also affect how an umbrella policy is structured. Reviewing your auto insurance coverage, homeowners liability protection, and other qualifying policies can help determine how an umbrella policy may fit into your broader insurance strategy.
If you are evaluating affordable umbrella insurance, the goal should be to compare the overall protection and policy terms rather than simply selecting the lowest available premium.

An umbrella policy works in conjunction with certain underlying insurance rather than replacing it. This makes it important to review the policies you already have before determining whether additional liability protection may be appropriate.
For example, your homeowners policy may provide personal liability protection for certain covered incidents involving your residence, while your auto policy provides liability protection for eligible vehicle-related claims.
Your personal auto insurance can therefore be an important part of the overall liability structure when evaluating umbrella coverage. The umbrella carrier may require specific underlying auto liability limits before the umbrella policy can provide additional protection.
The same principle can apply to other qualifying underlying policies. Requirements can vary by insurer and policy, so reviewing the specific conditions is important.
An umbrella policy should also be reviewed whenever your underlying coverage changes. Increasing or decreasing auto liability limits, purchasing another vehicle, acquiring property, or changing other insurance arrangements can affect how your overall liability protection is structured.
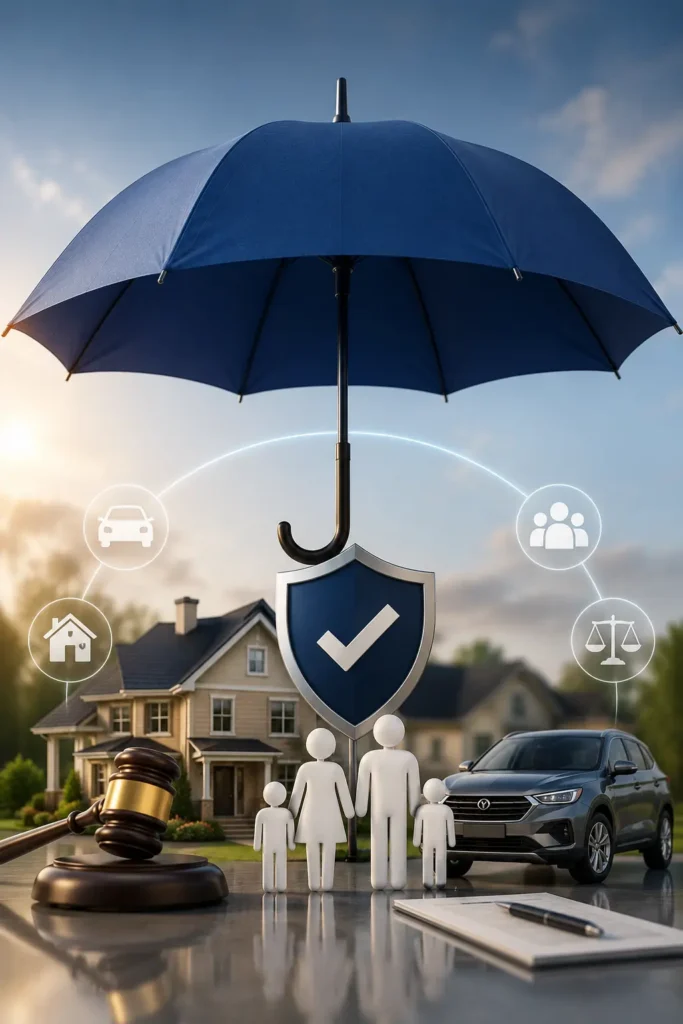
Coverage For Businesses Of All Sizes
A significant liability claim can create financial pressure that extends beyond the limits of a standard homeowners or auto policy. Medical expenses, property damage, legal defense, and other covered liabilities can become substantial depending on the circumstances of a claim.
The purpose of an umbrella policy is to provide an additional layer of liability protection for eligible covered claims once qualifying underlying limits have been exhausted.
This additional layer can be particularly relevant when an individual’s assets or potential financial exposure are substantial enough that the limits of their primary policies may not provide the level of protection they want.
However, umbrella insurance should not be viewed as unlimited protection. Every policy has specific terms, exclusions, conditions, limits, and eligibility requirements.
A proper review should therefore consider the individual’s underlying insurance, assets, lifestyle, properties, vehicles, and potential liability exposures.
Blue Peak Risk Advisors can help you review these factors and understand how umbrella coverage may fit into your broader insurance planning services.

FAQ’s
Umbrella insurance is additional personal liability coverage that can provide protection above certain limits of qualifying underlying policies, such as homeowners or auto insurance.
It is designed to supplement existing liability coverage rather than replace the underlying policies.
Umbrella insurance coverage depends on the specific policy. It may provide additional liability protection for certain covered claims that exceed the limits of qualifying underlying policies.
The exact protection, exclusions, conditions, and underlying insurance requirements vary by policy and carrier.
The umbrella insurance cost depends on factors such as the coverage limit, number of properties and vehicles, household drivers, underlying insurance, claims history, and other underwriting considerations.
Comparing multiple options can help you evaluate both the premium and the protection provided.
A homeowners or auto policy may provide liability protection, but an umbrella insurance policy can provide an additional layer above certain underlying limits.
Whether additional coverage is appropriate depends on your assets, potential liability exposure, existing limits, and individual circumstances.
The appropriate amount of umbrella policy coverage depends on your assets, properties, vehicles, lifestyle, potential liability exposure, and the limits of your underlying insurance.
A review of your existing policies and personal circumstances can help you evaluate what level of additional protection may be appropriate.
Your home, vehicles, properties, and personal assets can all contribute to your overall liability exposure. Reviewing your insurance as a complete strategy can help you understand where your existing protection ends and where additional coverage may be appropriate.
Blue Peak Risk Advisors helps individuals and families compare umbrella insurance options and understand how additional liability protection can work alongside their existing policies.
Whether you are reviewing umbrella insurance cost, comparing affordable umbrella insurance, or evaluating your existing liability limits, a professional coverage review can help you better understand your available options.
BLUE PEAK RISK ADVISORS
Get a quick insurance estimate based on your coverage needs. It only takes a few simple questions.
Start My Estimate Get a quick insurance cost estimate →Free estimate. No obligation.